Medical Design and Outsourcing

  • Home
  • Medical Device Business
    • Mergers & Acquisitions
    • Financial
    • Regulatory
  • Applications
    • Cardiovascular
    • Devices
    • Imaging
    • Implantables
    • Medical Equipment
    • Orthopedic
    • Surgical
  • Technologies
    • Supplies and Components Index
    • Contract Manufacturing
    • Components
    • Electronics
    • Extrusions
    • Materials
    • Motion Control
    • Prototyping
    • Pumps
    • Tubing
  • MedTech Resources
    • Medtech Events in 2026
    • The 2026 Medtech Big 100
    • Medical Device Handbook
    • MedTech 100 Index
    • Subscribe to Print Magazine
    • DeviceTalks
    • Digital Editions
    • eBooks
    • Educational Assets
    • Manufacturer Search
    • Podcasts
    • Webinars / Digital Events
    • Whitepapers
    • Voices
    • Views
    • Video
  • 2026 Leadership
    • 2025 Winners
    • 2024 Winners
    • 2023 Winners
    • 2022 Winners
    • 2021 Winners
  • Women in Medtech
  • Advertise
  • Subscribe

Private equity’s on the hunt for big profits in medtech

Two lawyers who work with private equity firms and medical device companies explain the PE business model.

August 12, 2026 By Jim Hammerand

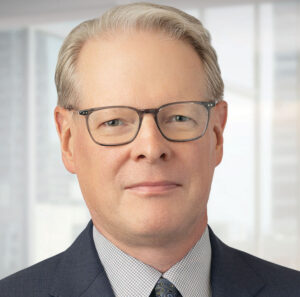
A photo of Fredrikson attorney Jamie Snelson.

Fredrikson attorney Jamie Snelson was previously in-house legal counsel for Medtronic. [Photo courtesy of Fredrikson]

Private equity firms are rolling up medtech suppliers and contract manufacturers, buying medical device developers, manufacturers and business segment spinoffs, and even taking over hospitals, physician practices and other medical device customers.

To learn more about PE firms, what they do and how they’re changing the medical device industry, Medical Design & Outsourcing spoke with two lawyers who work with medical device OEMs, their outsourcing partners and PE firms.

Minimally invasive medtech: Watch video replays of our 2026 MDO Min-Vasive Medtech webinar series with experts in robotics, imaging and cardiac devices

Jamie Snelson and Carl Numrich are shareholders at Minneapolis-based law firm Fredrikson, which represents private equity platform sponsors including KKR (which is buying CDMO Integer for $5.7 billion), Bain Capital and Morgan Stanley.

Snelson works with medtech OEMs and was previously in-house legal counsel for Medtronic. He’s helped the world’s largest medical device company buy public companies and stock and assets of private businesses, along with dispositions, strategic investments and technology licensing deals.

Numrich represents PE firms and investment firms such as Audax, Arcline, Kolos Partners and Goldner Hawn.

The following has been lightly edited for clarity and space.

MDO: How does the private equity model work? Where’s the profit in it and how do they realize it?

A photo of Fredrikson attorney Carl Numrich.

Fredrikson attorney Carl Numrich [Photo courtesy of Fredrikson]

Numrich: “Private equity is about finding a portfolio company on which they can build and drive growth for an eventual exit. Private equity funds are largely looking for free cash flow and modeling valuations based on EBITDA (earnings before interest, taxes, depreciation and amortization), with the idea that they’re growing that EBITDA both organically through smart acquisitions, scale synergies — just like any strategic investor would do — but then also doing it through scale, through add-on acquisitions and the like to hopefully down the road be able to sell a portfolio company that they’ve grown where the sum of the parts is greater. … In the PE space if you’re doing a roll-up of home services businesses, for example, bigger is almost certainly better and scale is almost certainly more. With regulated assets like we see in the medtech and healthcare space, that has to be done thoughtfully and strategically in a way that ensures those add-ons and growth is actually accretive and not creating integration complexity and other issues down the road.”

Snelson: “I think about the difference between strategics versus private equity, particularly in medical technology, and the time horizon is really a key difference. Often our strategic clients are investing in a much longer term proposition. They’re filling out the bag. They want a more complete product offering for their sales channel to benefit from, and not just in the next one year, three years, five years, but for the foreseeable future. Durability of growth will be of increasing value, no matter the buyer. Private equity is often looking at a shorter hold period and what’s going to result in the greatest value accretion for the platform during that hold period. Something that will get off the ground running. It really needs to be commercial right away, and something that’s going to contribute to the growth of the platform in the near term.”

What kind of return is a PE firm looking for and what levers can they throw to accomplish that?

Numrich: “It depends on the fund, on the strategy and a number of factors. But the idea in private equity is they’re aiming for returns that aren’t accessible in other places in the market. Private equity investments are by their nature riskier and allows investors to access investments you can’t get in the public markets, and with that comes higher returns … much higher than you’d see other places.”

Snelson: “On the revenue side, there are benefits to an acquisition (both for private equity and strategic) through expansion of the product bundle, geographic expansion can sometimes be a secret to unlocking revenue growth, new distribution channels, greater brand recognition. Sometimes it is scale and profile that can increase the value proposition by virtue of M&A. But also on the cost side, you could refer to them as cost synergies. Sometimes that’s just procurement leverage, better terms from suppliers, shared services across a broader base, back office consolidation and things like that. There are all kinds of levers that can be pulled depending on acquirer’s situation and what the target company brings to the table.”

Can you ballpark the return to LPs that PE firms are typically looking for?

Snelson: “It varies and it’s probably more variable over the past five years than it was previously, but certainly a multiple of the LP investment in a five- to perhaps seven-year hold period, LPs are looking for a multiple of what they put into the fund.”

Numrich: “I would guess you’re looking somewhere in the 10% to 12% range if you looked at a typical fund and what people are looking to to return. But you see funds that hit home runs and return at much higher rates.”

The hold window I’ve heard for PE is usually three to five years, but is that changing?

Numrich: “It depends on the vehicle, again. But a typical hold period is is three to five years, maybe five to seven, with a fund life closer to 10. So throughout the life of a fund, you may have a fund where LPs are invested on a 10-ish-year horizon. Within that fund, the PE firm is going to do — it depends on the firm — but call it five to 10 platforms per fund and then each of those platforms may do two to five add-ons a year. Each of those platforms may be held on for three to five to maybe seven years on the long-end horizon, and they’ll be liquidating at various points throughout the fund life. And then the firm participates in the economics through both their management fee for the money the PE firm is managing on behalf of the LPs, and then based on a return over certain hurdle rates in the fund, and those will those will vary largely depending the terms of the LP agreement. There are a variety of models for how that looks. It gets very complicated. But that’s the way to think about it: The private equity funds are participating in a management fee plus a return over certain hurdle rates on expectations on the fund.”

Is there a standard for the management fee like the “two and twenty” rule for venture capital and hedge funds?

Snelson: “Two and twenty is what you hear. That’s always the rule of thumb, though that’s negotiated and there’s lots of variability in what that looks like, how the hurdles look. There are also differences in whether the return is on an investment-by-investment basis or on the fund performance overall. Those are the American and European models. But it depends on the specific fund and and often the sophistication of investors, the size of your fund, your history with your LPs, etc.”

And just to be clear, “two and twenty” means 2% of assets under management plus 20% of the profits or returns?

Numrich: “Yes, with the addition on the end that it’s over a hurdle rate, so it’s often 20% after you’ve returned money plus some return to your LPs.”

This is the first of a series of articles from our interview. Read the second part here and  subscribe to our free newsletter to watch for the next one.

About The Author

Jim Hammerand

Jim Hammerand is the managing editor of Arrowfly's Medical Design & Outsourcing, where he leads coverage of medtech innovation, design, engineering and manufacturing. He also reports breaking news at Arrowfly's MassDevice and contributes to our DeviceTalks podcasts and live events. Hammerand has more than two decades of journalism experience spanning newspapers, magazines, websites, live events, radio and TV news. For nearly a decade, Hammerand reported and edited business news for American City Business Journals as a reporter and digital editor at the Minneapolis/St. Paul Business Journal and then as managing editor of the Puget Sound Business Journal in Seattle. He holds degrees in journalism and management from the University of Minnesota and has won journalism awards from the Society of Professional Journalists, American Society of Business Publication Editors, and Trade, Association, Business Publications International. Connect with him on LinkedIn or by email at [email protected].

Related Articles Read More >

PE firm Vance Street merges medtech suppliers MRPC, PDC and Injectech
A photo of Fredrikson attorney Carl Numrich.
Data breaches are killing more deals than anything else, these M&A lawyers say
An image of the September 2026 Medical Design & Outsourcing magazine featuring the Medtech Big 100 ranking of the world's largest medical device companies.
September 2026 issue: The MDO Medtech Big 100 breaks $500 billion
A photo of Fredrikson attorney Carl Numrich.
What private equity means for medtech OEMs, suppliers and their employees
“mdo
EXPAND YOUR KNOWLEDGE AND STAY CONNECTED
Get the latest medical device business news, application and technology trends.

DeviceTalks Weekly

See More >

MDO Digital Edition

Digital Edition

Subscribe to Medical Design & Outsourcing. Bookmark, share and interact with the leading medical design engineering magazine today.

MEDTECH 100 INDEX

Medtech 100 logo
Market Summary > Current Price
The MedTech 100 is a financial index calculated using the BIG100 companies covered in Medical Design and Outsourcing.

New MedTech Resource

Medical Tubing

MassDevice

Mass Device

The Medical Device Business Journal. MassDevice is the leading medical device news business journal telling the stories of the devices that save lives.

Visit Website
MDO ad
Medical Design and Outsourcing
  • MassDevice
  • DeviceTalks
  • MedTech100 Index
  • Medical Tubing + Extrusion
  • Medical Design Sourcing
  • Drug Delivery Business News
  • Drug Discovery & Development
  • Pharmaceutical Processing World
  • R&D World
  • About Us/Contact
  • Advertise With Us
  • Subscribe to Print Magazine
  • Subscribe to our E-Newsletter
  • Listen to our Weekly Podcasts
  • Join our DeviceTalks Tuesdays Discussion

Copyright © 2026 Arrowfly, LLC. All Rights Reserved. The material on this site may not be reproduced, distributed, transmitted, cached or otherwise used, except with the prior written permission of Arrowfly LLC. Site Map | Privacy Policy | RSS

Search Medical Design & Outsourcing

  • Home
  • Medical Device Business
    • Mergers & Acquisitions
    • Financial
    • Regulatory
  • Applications
    • Cardiovascular
    • Devices
    • Imaging
    • Implantables
    • Medical Equipment
    • Orthopedic
    • Surgical
  • Technologies
    • Supplies and Components Index
    • Contract Manufacturing
    • Components
    • Electronics
    • Extrusions
    • Materials
    • Motion Control
    • Prototyping
    • Pumps
    • Tubing
  • MedTech Resources
    • Medtech Events in 2026
    • The 2026 Medtech Big 100
    • Medical Device Handbook
    • MedTech 100 Index
    • Subscribe to Print Magazine
    • DeviceTalks
    • Digital Editions
    • eBooks
    • Educational Assets
    • Manufacturer Search
    • Podcasts
    • Webinars / Digital Events
    • Whitepapers
    • Voices
    • Views
    • Video
  • 2026 Leadership
    • 2025 Winners
    • 2024 Winners
    • 2023 Winners
    • 2022 Winners
    • 2021 Winners
  • Women in Medtech
  • Advertise
  • Subscribe