Our authoritative ranking and analysis of the world’s largest medical device companies finds sales, R&D spending and employment on the upswing.
By Managing Editor Jim Hammerand and Associate Editor Skyler Rivera
For more analysis and data from our 2026 Medtech Big 100 ranking of the world’s largest medical device companies, download our free special report here.
The Medical Design & Outsourcing Medtech Big 100 ranking of the world’s largest medical device companies by revenue is bigger than ever, breaking the half-trillion-dollar mark for the first time. Research and development (R&D) spending growth is also up after last year’s big slowdown, and total employment grew nearly 3% year over year.
The Medtech Big 100 is an annual index that measures and tracks the medical device industry through its 100 largest businesses, including OEMs, medtech segments of larger, diversified companies like Johnson & Johnson and Abbott, and one pure-play medical device contract manufacturing and development organization.
The 2026 Big 100 covers financial results as recent as April 2026, but most companies reported results for calendar year 2025. This year’s list includes three new companies in the top 50, including Medtronic’s diabetes business, MiniMed, which landed at No. 40 after its IPO with $3.1 billion in revenue. Medtronic is still reporting that revenue in its total, keeping it atop our ranking as the world’s largest medical device company with revenue of $36.4 billion.
With 8% revenue growth, Medtronic grew faster than No. 2 Johnson & Johnson MedTech (up 6% to $33.8 billion) and expanded its sales lead by nearly a billion dollars to $2.6 billion.
Read more in the September 2026 Medtech Big 100 issue of Medical Design & Outsourcing magazine and learn more about the project from our editors in this on-demand webinar replay
Who’s in and who’s out
Several companies that were purchased by private equity in recent years dropped off this year’s Medtech Big 100 because they did not share their latest financial results.
They are: Owens & Minor (formerly No. 13, bought by Platinum Equity at the end of 2025), Cordis (formerly No. 75, purchased by Hellman & Friedman in 2021), Topcon’s eye care business (formerly No. 87, went private in deal partially funded by KKR and JIC Capital in 2025), ZimVie (formerly No. 91, purchased by Archimed in 2025), and Highridge Medical (formerly No. 97, purchased by H.I.G. Capital in 2024).
The same might happen to Integer, the CDMO at No. 56 that plans to sell to KKR for $5.7 billion in a deal that could close by the end of 2026.
Bruker is also off this year’s ranking because their medical device revenue was not available.
New names on the list beyond MiniMed include Zoll Medical, Karl Storz’s medical segment, Plexus’ healthcare and life sciences segment, Ascensia Diabetes Care, Konica Minolta’s healthcare segment and Agfa-Gevaert’s radiology solutions segment.
Big 100 revenue is up
Total revenue for the 2026 Medtech Big 100 was nearly $519.1 billion, up 6% from $486.7 billion last year. Eighty-six companies reported year-over-year sales increases, 12 reported decreases and two did not provide prior-year revenue for comparison: Zoll and Cook Medical, the latter of which previously only shared revenue for its parent company.
Organ transplantation device developer and transportation company TransMedics reported the largest year-over-year revenue increase at 37%. The Organ Care System (OCS) developer got into another highly regulated industry — aviation — with its purchase of a charter flight operator in 2023.
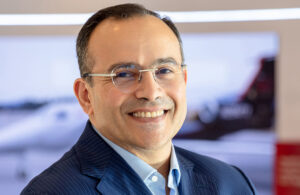
TransMedics founder, CEO and President
Waleed Hassanein [Photo courtesy of TransMedics]
“The impact of our work is measurable in lives saved and transplants performed, but we remain driven by the opportunities in front of us,” he told investors ahead of their May 2026 annual meeting. “Tens of thousands of patients remain on transplant waiting lists in the U.S. alone, and we believe TransMedics is uniquely positioned to close that gap.”
Other companies leading revenue growth were Glaukos (32%), Insulet (31%), iRhythm (26%), Alphatec Holdings (25%), BD’s medical and interventional segments (23%), Asahi Intecc’s medical device business (23%), Medacta (21%), Intuitive Surgical (21%), Si-Bone (20%) and Boston Scientific (20%).
Teleflex reported the biggest revenue decrease at 35% as it sold its Acute Care, Interventional Urology and OEM businesses for $2 billion. PE firms Montagu and Kohlberg bought the OEM contract development and manufacturing business.
Masimo followed with a 27% decrease in revenue. The home health monitoring company, which sold its Sound United consumer audio business in 2025, was purchased by Danaher in June 2026 and might not make our 2027 ranking if financial results aren’t available.
Rounding out the rest of the largest sales decreases are Agfa-Gevaert’s radiology solutions segment (down 13%), Mindray (down 9%), Konica Minolta’s healthcare segment (down 7%), ICU Medical (down 6%) JMS Co. (down 4%), Nikkio’s medical unit (down 4%), Embecta (down 4%) and Dentsply Sirona (down 3%).
R&D spending climbs
Seventy-six Medtech Big 100 companies disclosed their annual R&D spending for a total of $32.2 billion.
That’s up 9% from last year, when 74 companies disclosed total R&D spending of $29.2 billion.
R&D spending as share of revenue has remained steady over the past three years at 6%.
Ten companies in the Medtech Big 100 spent more than $1 billion on R&D:
- Medtronic ($2.9 billion, up 5%)
- J&J MedTech ($2.8 billion, down 23%)
- Siemens Healthineers ($2.2 billion, up 7%)
- Boston Scientific ($2.1 billion, up 27%)
- Royal Philips ($1.9 billion, up 2%)
- Abbott medical device segment ($1.8 billion, up 13%)
- Stryker ($1.6 billion, up 11%)
- Intuitive Surgical ($1.3 billion, up 15%)
- GE HealthCare ($1.3 billion, down 4%)
- Edwards Lifesciences ($1.1 billion, up 3%)
J&J MedTech was the top R&D spender last year at $3.7 billion, but its year-over-year decrease of 23% was one of the largest among all Big 100 companies.
Explaining that decrease in its most recent annual report, J&J pointed to two expenses from 2024: a $500 million in-process R&D expense from the V-Wave acquisition and a $300 million Laminar milestone.
J&J MedTech’s R&D spending equaled 8% of revenue in 2025, 12% in 2024, 10% in 2023 and 9% in 2022. J&J “remains committed to investing in research and development with the aim of delivering high quality and innovative products,” the company said in the filing.
Employment grows
The 2026 Medtech Big 100 list has a total employment of 1.3 million, up 3% from the year before. But only 81 companies offered headcounts (compared to 83 the year before), and some companies rounded to the nearest thousand rather than offering precise numbers.
Insulet led the way on workforce growth, expanding its workforce by 39% to about 5,400. Close behind were TransMedics (up 23% to 898), iRhythm (up 20% to 2,400) and LivaNova (up 14% to 3,300).
Masimo reported the greatest headcount decrease (down 39% to 2,200 employees), followed by ICU Medical (down 13% to 13,000) and Embecta (down 12% to 1,850).
The Medtech Big 100 companies with the most employees are Medtronic (101,369, up 1%), Siemens Healthineers (74,000, up 3%), B. Braun (66,821, up 4%) and Royal Philips (65,340, down 4%).
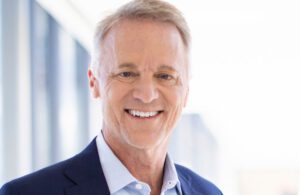
Boston Scientific Chair and CEO Mike Mahoney [Photo courtesy of Boston Scientific]
“We have an insatiable desire to be a large company, but not a large slow company,” CEO Mike Mahoney said about Boston Scientific’s culture earlier this year. “We really put a premium on appropriate speed and agility — trying to constantly root out bureaucracy — and appropriate risk-taking. [We] don’t want to just be a good company. We want to be the best company. … We want to win.”
For more analysis and data from our 2026 Medtech Big 100 ranking of the world’s largest medical device companies, download our free special report here.